Exclusive Interview: ICBC International's Cheng Shi on the Rare Simultaneous Strength of the RMB and the US Dollar
Since the start of 2026 (through October 13), the US dollar index has risen about 4% while the RMB has appreciated 4.4% against the dollar. The RMB and the US dollar strengthening in tandem has occurr
Since the start of 2026 (through October 13), the US dollar index has risen about 4% while the RMB has appreciated 4.4% against the dollar. The RMB and the US dollar strengthening in tandem has occurred only twice since China's 2015 exchange rate reform, the previous instance being in 2021.
Cheng Shi, chief economist at ICBC International, describes the simultaneous strengthening of the RMB and the dollar as "moving in parallel on different tracks." In an exclusive interview with Jiemian News, he noted that while the two currencies are moving in the same direction on the surface, the drivers differ: dollar strength is mainly underpinned by US real interest rates, whereas RMB strength is driven more by improved onshore foreign exchange supply and demand and the release of corporate settlement demand, among other factors.
"This round of RMB appreciation is closely tied to changes in the foreign exchange receipts and payments behavior of domestic companies," Cheng said. In January-August 2026, banks' net foreign exchange settlement and sales on behalf of clients reached US$397.6 billion, the highest level for the period since 2005. A further comparison of trade and settlement data shows that the improvement in FX supply and demand reflects both export revenue and changes in corporate settlement behavior. In the first eight months of the year, China's goods trade surplus grew 3.1% year on year, while banks' foreign exchange settlements on behalf of clients rose 31.9%. The settlement ratio rose 2.3 percentage points and the sales ratio fell 2.2 percentage points, reflecting a phased adjustment in how companies allocate funds between domestic and foreign currencies.
On concerns that export momentum may fade and settlement activity weaken, Cheng said phased settlement changes may affect FX supply and demand, but can hardly determine the medium- and long-term path of the exchange rate on their own.
"China's export competitiveness has structural support, with fast growth continuing in high-end manufacturing, mechanical and electrical products and emerging industries, and continued market diversification. Beyond trade, cross-border investment, financial market performance, corporate FX risk management and changes in the international financial environment all influence the RMB exchange rate. The RMB has strong fundamental support, the FX market is operating in a more mature way, and the currency is expected to maintain two-way fluctuation with greater flexibility," Cheng said.
He also noted that the RMB exchange rate's sensitivity to changes in the China-US interest rate differential has declined this year, as has the linkage between Chinese government bond yields and US Treasury yields, consistent with the long-term trend of a deepening FX market and greater RMB flexibility.
Cheng pointed out that interest rate differentials are an important factor for exchange rates but not the only one. Differentials affect exchange rates through cross-border capital allocation, carry trades and market expectations, and that transmission is also shaped by risk premia, exchange rate expectations, market structure and companies' actual FX receipts and payments. There is therefore no stable, one-way linear relationship between differentials and exchange rates. From a macro policy standpoint, the changing link between the exchange rate and interest rates is positive: the pass-through from external rate changes to domestic financial conditions may become milder, creating favorable conditions for monetary policy to focus more on domestic economic performance and prices.
Recently, debate over the RMB's equilibrium value has intensified. The International Monetary Fund (IMF), for the first time in 14 years, assessed China's external position as "stronger than warranted," estimating a median real effective exchange rate gap of -21.3%. China's central bank argues that equilibrium exchange rate models have limitations and that external imbalances cannot simply be attributed to the exchange rate.
Cheng said equilibrium exchange rate assessments are highly complex and uncertain, and model results need to be analyzed in light of economic structure, parameter assumptions and actual market conditions. For a large open economy like China that is undergoing economic transformation and upgrading, factors such as technological progress, industrial upgrading, services trade development and RMB internationalization all affect model parameters and their applicability.
He stressed that China's internal and external rebalancing relies first on domestic demand reforms rather than the exchange rate tool. "The continued improvement in China's internal and external balance fundamentally rests on transforming the growth model, unlocking domestic demand and high-level opening-up. The exchange rate, through market-based mechanisms, plays the role of an automatic stabilizer for the macroeconomy and the balance of payments," Cheng said.
Jiemian News: You describe this round of simultaneous dollar and RMB strength as "moving in parallel on different tracks." How should we understand that? Does it mark a turning point at which the RMB exchange rate shifts from passively following external cycles to endogenous, self-determined pricing?
Cheng Shi: Since the 2015 reform, simultaneous RMB and dollar strength has been rare, occurring only in 2021 and 2026. The RMB also appreciated against the dollar in 2025, but the dollar index fell 9.4% that year and the RMB's exchange rate index against a basket of currencies also declined, so appreciation against the dollar was mainly driven by dollar weakness. This year is different: while the dollar index has risen, the RMB has strengthened against both the dollar and a basket of currencies, reflecting a more visible role for China's own market supply and demand factors.
Our empirical research finds that dollar strength is mainly underpinned by US real interest rates, while RMB strength is driven more by improved onshore FX supply and demand and the release of corporate settlement demand. At the same time, the RMB's sensitivity to the China-US interest rate differential and to the dollar index has declined. This is consistent with the long-term trend of a deepening FX market and steadily increasing RMB exchange rate flexibility.
In recent years, the depth and breadth of China's FX market have continued to expand, companies' FX risk management capabilities have steadily improved, cross-border RMB use has become more widespread, and market supply and demand play a greater role in RMB exchange rate formation. Over a longer horizon, the RMB exchange rate is jointly influenced by economic fundamentals, the balance of payments, market expectations and the global financial environment. The current dual-strength configuration reflects how the relative importance of these factors has shifted at different stages. As China's high-quality development advances, the fundamental support for the RMB will be further consolidated, helping keep the exchange rate basically stable at a reasonable and balanced level.
Jiemian News: With the China-US interest rate differential inverted, the RMB has kept appreciating against the trend, defying the traditional logic that an inverted differential means a weaker RMB. Why are the old exchange rate models breaking down?
Cheng Shi: From an economic theory perspective, the interest rate differential is one important factor for exchange rates, but not the only one. Differentials affect exchange rates through cross-border capital allocation, carry trades and market expectations, and this transmission process is also shaped by risk premia, exchange rate expectations, market structure and companies' actual FX receipts and payments. There is therefore no stable, one-way linear relationship between differentials and exchange rates.
Our research finds that the RMB's sensitivity to differential changes has declined, while the influence of onshore settlement demand on the exchange rate has increased. This shows that RMB exchange rate formation is now driven by more diverse market factors. Using weekly changes in the USD/CNY exchange rate as the object of study, and examining the influence of both the dollar index and the China-US 10-year government bond yield spread, the results show that in 2023-2024, every 10 basis point widening in the 10-year spread was associated with an average RMB depreciation of about 0.08% against the dollar, a statistically significant relationship. But since 2025, the effect of differential changes on the RMB exchange rate has no longer been significant. The RMB's linkage with the dollar index has also weakened: in 2023-2024, a 1% rise in the dollar index was associated with average RMB depreciation of about 0.32% against the dollar, a figure that has fallen to 0.15% since 2025. The dollar index still has some explanatory power, while that of the interest rate differential has clearly declined, and the relative importance of exchange rate drivers is changing.
Notably, this change is also reflected in the linkage between the Chinese and US bond markets. Our research finds that the sensitivity of China's 10-year government bond yield to changes in the US 10-year Treasury yield fell from 0.20 in 2015-2019 to 0.04 in 2023-2024 and further to 0.02 since 2025. This suggests China's bond market increasingly reflects domestic economic fundamentals, liquidity supply and demand and the policy environment, with a weaker direct impact from external interest rate changes.
From a macro policy perspective, the change in the exchange rate-interest rate linkage is positive. As RMB exchange rate flexibility increases and FX market supply and demand become more diverse, the pass-through from external interest rate changes to domestic financial conditions may become milder, creating favorable conditions for monetary policy to focus more on domestic economic performance and the price situation.
In terms of economic structure, China has a complete industrial system, strong export competitiveness and a growing domestic market, providing fundamental support for the RMB exchange rate. At the same time, rising cross-border RMB use and improving corporate FX risk management capabilities also help reduce the impact of short-term differential changes on the FX market. Analysis of the RMB exchange rate therefore requires a comprehensive consideration of economic fundamentals, the balance of payments, market supply and demand and global financial conditions. As exchange rate marketization reform continues to deepen, the importance of a multi-factor analytical framework will only increase.
Jiemian News: With weak real RMB interest rates and a deeply inverted China-US interest rate differential, why is corporate willingness to settle foreign exchange stronger than ever?
Cheng Shi: Stronger corporate settlement demand reflects phased changes in FX market supply and demand, and also shows that companies are managing FX risk more proactively in an environment of two-way exchange rate fluctuation. It should be noted that settlement volumes are affected by multiple factors including business cycles and market conditions, and should not be simply read as a one-sided judgment on the future direction of the exchange rate.
First, exports have remained resilient, providing the actual foreign exchange revenue base for corporate settlement. In recent years, China's export structure has continued to improve, the competitiveness of high-technology and mechanical and electrical products has steadily increased, export markets have become more diverse, and companies' cross-border operations have remained active. Looking at the actual data, this round of RMB strengthening is closely tied to changes in the foreign exchange receipts and payments behavior of domestic companies. In January-August 2026, banks' net FX settlement and sales on behalf of clients reached US$397.6 billion, well above US$44.4 billion in the same period of 2025 and a marked improvement from a US$166.3 billion deficit in the same period of 2024, the highest level for the period since 2005. A comparison of trade and settlement data shows that the improvement in FX supply and demand reflects both export revenue and changes in corporate settlement behavior. Over the same period, China's goods trade surplus grew 3.1% year on year, while banks' FX settlements on behalf of clients reached US$2,034.1 billion, up 31.9%. The settlement ratio rose 2.3 percentage points and the sales ratio fell 2.2 percentage points, reflecting a phased adjustment in companies' allocation of domestic and foreign currency funds.
Second, corporate settlement decisions are shaped by both the return on holding foreign exchange and exchange rate risk. Companies assess the holding cost and potential FX gains or losses of assets in different currencies. In a static calculation assuming interest accrues at the start-of-year 1-year government bond yield and ignoring transaction costs — with 1-year government bond yields of 1.34% in China and 3.48% in the United States at the end of 2025 — holding dollars from the start of the year through September 24 would have yielded about 1.57 percentage points of extra carry, while the RMB appreciated 4.1% against the dollar over the same period. Converted into RMB, holding dollars produced a return of -1.5%, while settling at the start of the year and holding RMB produced a return of 0.98%, a gap of about 2.5 percentage points. This shows that when evaluating foreign exchange asset allocation, companies need to weigh interest rates, exchange rates and funding needs together.
Third, corporate settlement also has clear operational characteristics: companies need to arrange domestic and foreign currency funds according to actual business needs. From a corporate perspective, further embracing a risk-neutral approach to foreign exchange, making reasonable use of FX derivatives and optimizing domestic and foreign currency asset-liability management can help reduce the impact of exchange rate volatility on business operations.
Jiemian News: If export momentum fades and corporate settlement activity weakens, could the current dual-strength configuration reverse quickly?
Cheng Shi: The RMB exchange rate is jointly affected by multiple factors; phased changes in settlement may affect FX supply and demand, but can hardly determine the medium- and long-term path of the exchange rate on their own. First, China's export competitiveness has strong structural support. In recent years, fast growth has continued in high-end manufacturing, mechanical and electrical products and emerging industries, and export market diversification has continued to advance, which helps strengthen the stability and resilience of foreign trade and provides fundamental support for the stable operation of the FX market. Second, the factors influencing the RMB exchange rate are increasingly diverse. Beyond trade receipts and payments, cross-border investment, financial market performance, corporate FX risk management and changes in the international financial environment all jointly affect the RMB exchange rate.
Overall, the RMB exchange rate has strong economic fundamental support, and the FX market is operating in a more mature way. As exchange rate marketization reform continues to deepen, the RMB exchange rate is expected to maintain two-way fluctuation and greater flexibility, remaining basically stable at a reasonable and balanced level.
Jiemian News: At the end of July this year, the IMF published its External Sector Report, assessing China's external position as "stronger than warranted" for the first time in 14 years and citing a median real effective exchange rate gap of -21.3%. On October 8, the People's Bank of China said in a policy stance document that external imbalances cannot simply be attributed to the exchange rate. Does the IMF model fall short in capturing China's economic structure?
Cheng Shi: Equilibrium exchange rate assessments are highly complex and uncertain, and model results need to be analyzed comprehensively in light of economic structure, parameter assumptions and actual market conditions.
First, the equilibrium exchange rate itself is difficult to observe directly. Different methods treat economic fundamentals, the savings-investment relationship, capital flows and exchange rate adjustment elasticity differently, so estimates may differ and need to be interpreted prudently. Second, there is no simple linear relationship between the current account and the exchange rate. From the macroeconomic identity, the current account balance corresponds to the gap between domestic saving and investment, and is affected by multiple factors including demographics, income distribution, industrial competitiveness, investment demand and the global division of labor. China has a complete industrial system, strong manufacturing competitiveness and a continuously upgrading export structure, all of which need to be fully considered when assessing external balance. Third, equilibrium exchange rate estimates usually rely on judgments about the medium- and long-term economic structure, and those structures are themselves constantly changing. For a large open economy like China that is in the process of economic transformation and upgrading, factors such as technological progress, industrial upgrading, services trade development and RMB internationalization all affect model parameters and their applicability.
Our research also observes, from the historical evolution of the RMB real effective exchange rate, that price factors and nominal exchange rate factors may have markedly different effects on the real effective exchange rate. According to the Bank for International Settlements broad real effective exchange rate index, the RMB real effective exchange rate fell from 107.31 in March 2022 to 86.18 in June 2025, a cumulative decline of 19.7%. Over the same period, the CFETS RMB exchange rate index fell 8.6%, so the decline in the real effective exchange rate was clearly larger than that of the nominal exchange rate. Rough estimates suggest that more than half of the decline in the real effective exchange rate is related to China's inflation running below that of major trading partners. This shows that changes in the real effective exchange rate reflect both nominal exchange rate adjustments and changes in relative domestic and foreign price levels. Analysis of real effective exchange rate changes therefore needs to combine price factors, industrial competitiveness and medium- and long-term economic fundamentals to comprehensively understand the economic meaning of the relevant indicators.
In policy practice, China maintains a managed floating exchange rate regime based on market supply and demand with reference to a basket of currencies, keeping the exchange rate flexible and allowing two-way fluctuation so that it plays the role of an automatic stabilizer for the macroeconomy and the balance of payments. As economic restructuring and high-level opening-up continue to advance, the RMB exchange rate will continue to be determined jointly by market supply and demand and multiple fundamental factors.
Jiemian News: What role should the exchange rate play in the process of internal and external rebalancing?
Cheng Shi: The continued improvement in China's internal and external balance fundamentally rests on transforming the growth model, unlocking domestic demand and high-level opening-up. The exchange rate, through market-based mechanisms, plays the role of an automatic stabilizer for the macroeconomy and the balance of payments.
First, the current account reflects multiple factors including a country's saving, investment and industrial structure. China has a super-large market, a complete industrial system and steadily improving technological innovation capacity, giving its trade competitiveness a strong structural foundation. As the stage of economic development changes, expanding household consumption, improving the quality of services supply and promoting effective investment will help drive domestic supply and demand toward a higher-level dynamic balance.
Second, expanding domestic demand and high-quality development are consistent over the long term. During the 15th Five-Year Plan period, as household incomes grow, the social security system improves, services consumption expands and new quality productive forces develop, the potential of the domestic market will be further released and the internal momentum for economic growth is expected to strengthen. This process will also promote growth in import demand and contribute positively to balanced global economic development.
Finally, as an important market price, the exchange rate can influence imports and exports, capital flows and resource allocation through relative price adjustments. Maintaining exchange rate flexibility helps the economy adapt to changes in the internal and external environment and also helps enhance monetary policy autonomy. As noted above, in recent years the RMB exchange rate's sensitivity to changes in the China-US interest rate differential has declined, and the linkage between Chinese government bond yields and US Treasury yields has also weakened markedly. This means domestic financial conditions can more fully reflect China's own economic growth, price changes and financing needs.
In the future, continued optimization of the economic structure and further development of the FX market will help keep the RMB exchange rate basically stable at a reasonable and balanced level, better serving the real economy and high-level opening-up.
Related Articles
PBOC Governor Pan Gongsheng Attends G20 FMCBG Meeting: China to Maintain a Moderately Accommodative Monetary Policy
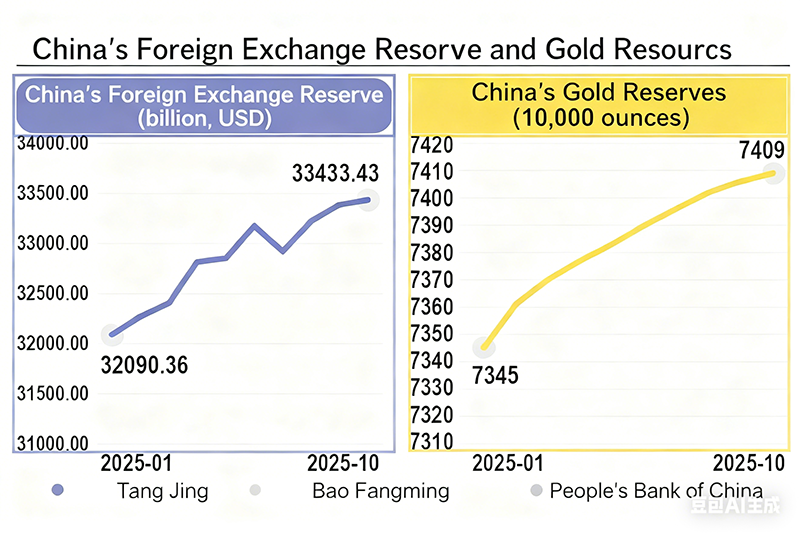
China's foreign exchange reserves exceed $3.3 trillion for three consecutive months as central bank adjusts pace of gold purchases
Global Financial Briefing | Friday, June 19, 2026: PBOC Fixing, CFETS RMB Index, MLF, LPR
China's M2 Up 7% YoY in Jan 2025, M1 Climbs 0.4%
State Administration of Foreign Exchange: Foreign investors net purchased $10.1 billion worth of domestic stocks and funds in the first half of the year